

English translation of the French original commentary, published by Fipeco on 29 October 2026. Terms in brackets give the French original where it helps.
Summary
“Tax expenditures” are legislative or regulatory provisions that depart from a benchmark tax system (the “tax norm”) and lead to a loss of tax revenue. When they concern personal income tax or corporate income tax they are sometimes called “tax loopholes” or “tax breaks” [niches fiscales]; the two terms are used interchangeably here. This note first presents the tax expenditures listed in the 2027 Finance Bill (PLF), with their cost in 2025 (the 2026 figure is still a forecast) and how they have changed since 2017. It then reviews tax expenditures in other countries.
- The list annexed to the 2017 Finance Bill identified 451 tax expenditures; the list annexed to the 2027 Finance Bill identifies 459.
- Estimating their cost is often difficult, and the 2027 Finance Bill provides a cost estimate for only 403 of them. For 83 of these, the figure is only an order of magnitude.
- Owing to a questionable change of method, the reported cost of VAT-related tax expenditures has been reduced by around €10bn since the 2024 Finance Bill.
- Using the previous costing method for VAT measures, total tax expenditures rose from €75.3bn in 2017 to more than €100bn in 2024, reaching €105.6bn in 2025. This is an increase from 3.3% of GDP in 2017 (excluding the CICE) to 3.5% in 2025, and from 12.4% of general government tax revenue in 2017 (excluding the CICE) to 13.1% in 2025.
- In a 2022 note based on official national tax expenditure reports, the IMF estimated their total cost at around 4% of GDP in the countries that publish such reports. The Council on Economic Policies (CEP), a Switzerland-based think tank, has built a database from these reports covering 218 jurisdictions. It shows that international comparisons are very difficult, because benchmark tax systems, and the scope and quality of the reports, vary widely.
- CEP has nevertheless built a transparency index for these reports, which ranks France ninth out of 116 countries assessed. The information published in France has its shortcomings, but the situation is worse in most other countries.
A) Tax expenditures in France
Further information on tax expenditures in France can be found in a dedicated fact sheet on FIPECO website.
- The number of tax expenditures
To determine whether a legislative or regulatory provision is a tax expenditure, one must first define the applicable tax norm from which it might depart.
Defining this benchmark is sometimes difficult, because it reflects views of taxation that are contested and may change over time. Whether the “family quotient” [quotient familial], which adjusts income tax to household size, is a tax break or not, for example, can be debated at length without reaching any consensus. In practice, the provisions treated as tax breaks are those on the list in Volume II of the Ways and Means report [rapport sur les voies et moyens] annexed each year to the Finance Bill, even though this list is open to question.
Indeed, the Ministry of Finance sometimes removes provisions from the list even though they still exist, and adds measures that already existed before.
Tax expenditures take many forms. The main ones are exemptions, allowances, deductions, reduced rates, additional half-shares under the family quotient (but not the “standard” half-shares), tax reductions and tax credits (see note 1).
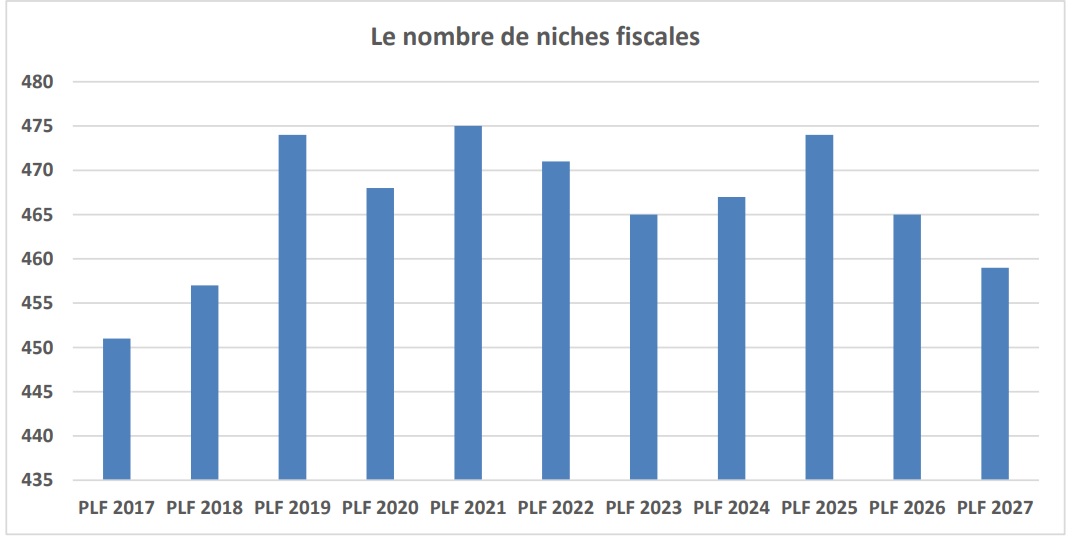
The report annexed to the 2017 Finance Bill listed 451 tax expenditures in September 2016; the report annexed to the 2027 Finance Bill listed 459 in September 2026. The number of tax breaks has therefore risen slightly since 2017.
Fig 1. Number of tax expenditures
Source: reports annexed to the Finance Bills.
The information in the Ways and Means reports does not make it easy to count the tax breaks that have been created or abolished, the pre-existing measures added to the list, or the measures removed from it that are still in force. In addition, a tax break may be abolished by a Finance Act and still appear on the list for several years afterwards because it continues to have a budgetary cost. The Tax Credit for Competitiveness and Employment (CICE), for instance, still appears on the 2027 Finance Bill list because of residual refunds to companies, even though it was abolished in 2019.
2. The cost of tax expenditures
a) Methodological difficulties
Volume II of the Ways and Means report annexed to the 2027 Finance Bill presents the budgetary cost of 403 tax breaks (out of 459) and the sum of these costs. The reliability of the total therefore depends on the relevance of the list and on how tax expenditures are split between those that can be costed and those that cannot (the largest ones, however, are always costed). The weakness of the costing methods adds to these sources of uncertainty.
Because it is often very difficult to estimate how tax measures affect taxpayer behaviour, their budgetary cost is always estimated on the assumption that behaviour does not change as a result of these measures.
On that basis, the cost of tax credits is easy to assess: it is enough to take taxpayers’ returns and add up the tax credits they claim and are granted.
Estimating the cost of tax reductions is harder, because they are capped at the amount of tax due before the reduction. It can nonetheless be done through simulations on a representative sample or on the full set of tax returns, as is the case for the cost of an allowance, a deduction or an additional half-share.
Exempt income, activities or assets are rarely reported in tax returns, and estimating their cost is often very difficult, or even impossible. The exempt amount has to be estimated from other tax data or from statistics such as the national accounts, and then the tax rate that would have applied without the exemption has to be applied to it, which is not always straightforward.
Estimating the cost of a reduced VAT rate applied to a particular activity is not easy either, since business tax returns generally do not allow it to be calculated. It is therefore estimated from consumption statistics rather than from tax returns. These statistics, however, cannot measure with sufficient precision the value of certain very specific purchases that benefit from a reduced rate.
Of the 403 tax breaks costed in the 2027 Finance Bill, the figure is only an order of magnitude for 83 of them.
b) The change of method in the 2024 Finance Bill
The cost of VAT-related tax expenditures was cut from around €20bn in previous Finance Bills to around €10bn in the 2024 Finance Bill, on the grounds that the State passes on about half of VAT revenue to social security and local government bodies, and that the cost of tax expenditures corresponds only to the share borne by the State.
This change of method is highly questionable. First, as shown in an earlier note, the cost of these tax expenditures is in fact borne by the State. Second, the cost to general government as a whole is indeed around €20bn, and this is the most relevant figure. Third, the new method is not applied to other taxes that are partly passed on to local authorities, which is inconsistent. Finally, since the Ministry of Finance does not publish a back series of tax expenditures for past years estimated using the new method, the costs shown in the 2024 to 2027 Finance Bills are not comparable with those in earlier Finance Bills.
In its report on the 2023 State budget, the Court of Audit [Cour des comptes] stressed that this “questionable” change of convention had “blurred” the picture of tax expenditures, and recommended that the Ministry of Finance return to the previous convention. It repeated this recommendation in its report on the 2024 budget. In the reports annexed to the 2026 and 2027 Finance Bills, the Ministry of Finance merely attached to the Ways and Means report an Excel file showing the cost of each VAT-related tax expenditure for general government as a whole.
In the rest of this note, unless otherwise stated, the cost of VAT-related tax expenditures to general government as a whole is used. The figures given for these provisions, and for the total cost of tax expenditures, therefore differ from those in the Ways and Means report of the 2027 Finance Bill.
c) The cost of tax expenditures in 2025
The cost of tax expenditures was €75.3bn in 2017. It exceeded €100bn for the first time in 2024 and reached €105.6bn in 2025 (compared with €91.7bn in the 2027 Finance Bill under the new method for VAT-related tax expenditures). This is an increase of €4.0bn compared with 2024 (€101.7bn).
The main taxes concerned in 2025 are:
- personal income tax: €44.6bn;
- taxes on both household income and company profits (industrial and commercial, agricultural and non-commercial profits): €13.9bn;
- corporate income tax: €4.4bn;
- VAT: €24.9bn;
- excise duties on energy products: €9.3bn.
The most costly tax expenditures in 2025 are:
- the research tax credit [crédit d’impôt recherche]: €7.3bn;
- the tax credit for employing domestic workers at home: €7.1bn;
- the 10% allowance on pensions and retirement income: €5.3bn;
- the reduced VAT rate on restaurant meals consumed on the premises: €4.8bn;
- the reduced VAT rate on housing maintenance works other than energy renovation: €4.7bn;
- the partial exemption from transfer duties on the transmission of businesses (the “Dutreil pact”): €3.8bn;
- the exemption of amounts paid under profit-sharing, employee participation and employee savings schemes: €3.1bn.
Twenty tax breaks cost more than €1.0bn each, while around a hundred cost less than €10m.
The cost of tax expenditures in 2026 is still a forecast, and the Ministry of Finance’s forecast for the current year is often underestimated.
d) Long-term trends
Measures are sometimes removed from the list of tax expenditures even though they still exist, and others are added even though they already existed. Costing methods have also changed at times. The costs shown in the reports annexed to successive Finance Acts therefore need to be adjusted to present trends on a constant basis (scope and methods). This has been done here to produce a series consistent with the list in the 2027 Finance Bill.
The resulting trends should nonetheless be treated with caution. Besides the inherent weakness of the estimates, they are affected to an unknown extent by changes in the costing methods for certain specific measures (the use of new data sources, for example).
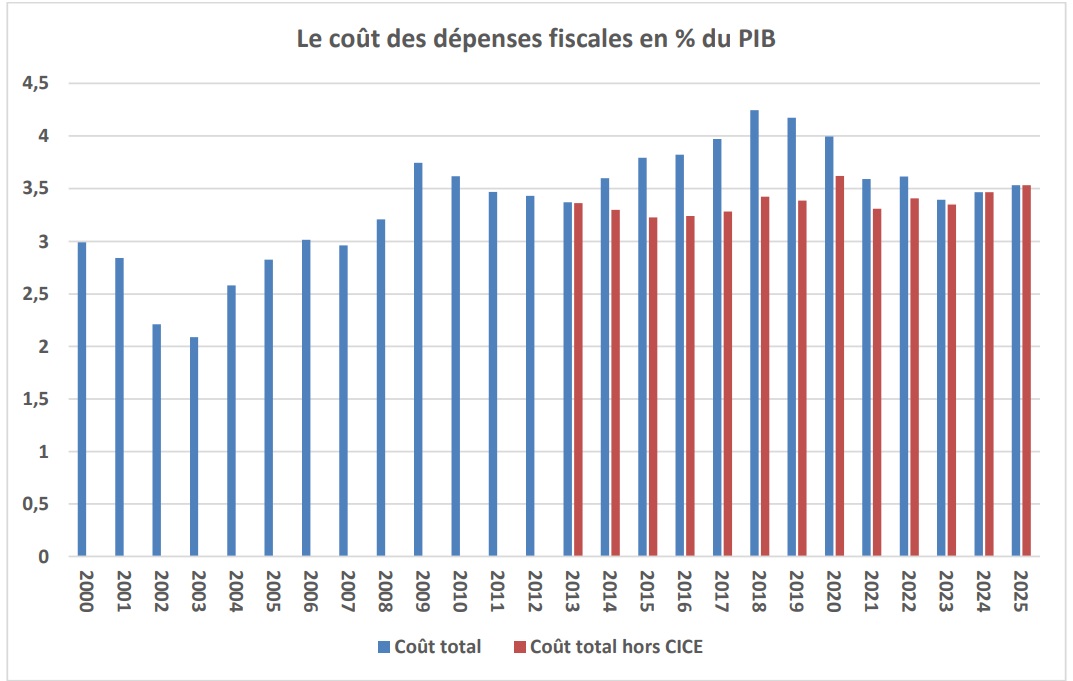
Fig 2. Cost of tax expenditures as a % of GDP, with and without the CICE
Sources: reports annexed to the Finance Bills (the cost shown in the 2024 to 2027 Finance Bills for 2022 to 2025 has been adjusted to include the full cost of VAT-related tax expenditures); FIPECO.
With these caveats, the data show a sharp rise in the cost of tax breaks as a share of GDP between 2003 and 2009. This was mainly due to tax credits, and coincided with the introduction of binding rules on budgetary spending. A decline followed until 2013. A new rise is observed from 2014 onwards. It is mainly due to the introduction of the CICE, but not only: the cost of tax expenditures excluding the CICE also increased from 2016. Leaving aside the peak in 2020, which was mostly the result of the fall in GDP, the cost of tax expenditures excluding the CICE rose slightly from 3.3% of GDP in 2017 to 3.5% in 2025.
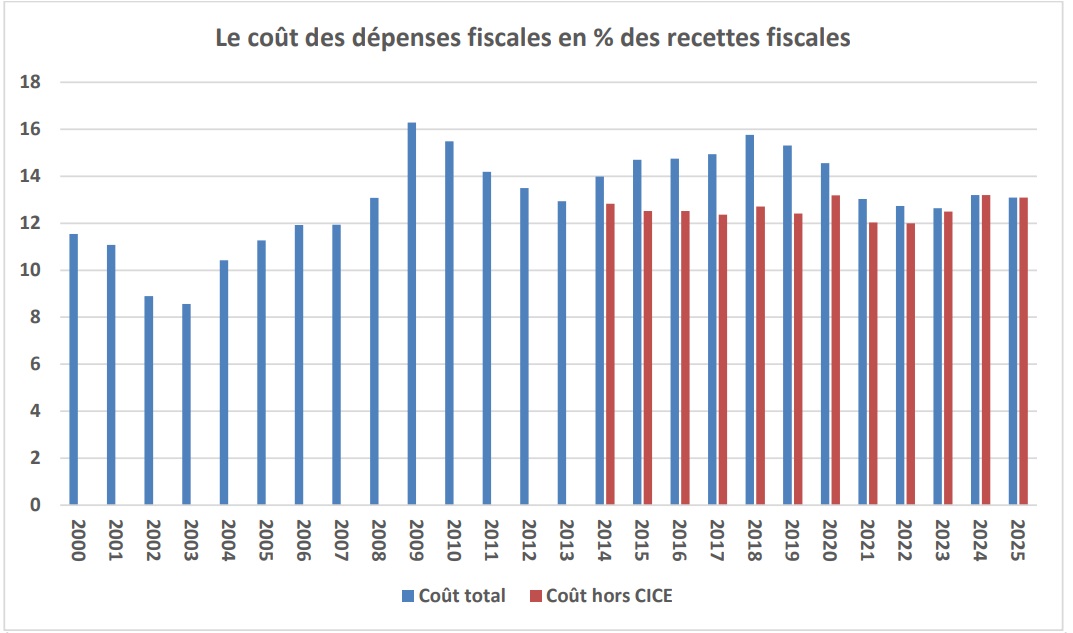
The cost of tax expenditures can also be expressed relative to general government tax revenue, as in the following chart, which calls for almost identical comments.
Fig. 3 Cost of tax expenditures as a % of tax revenue
Sources: reports annexed to the Finance Bills (the cost shown in the 2024 to 2027 Finance Bills for 2022 to 2025 has been adjusted to include the full cost of VAT-related tax expenditures); FIPECO. Tax revenue is that of general government as a whole.]
B) Tax expenditures in other countries
The concept of “tax expenditures” first appeared in budget documents in the United States and Germany in the late 1960s, and many countries now publish tax expenditure reports. Everywhere, they are defined as departures from benchmark tax systems.
1. The work of the European Commission and the IMF
In the European Union, a 2011 directive required Member States to report information on their tax expenditures to the European Commission. The Commission’s 2014 report recalled the methodological difficulties set out above. It found that two groups of countries stood out with regard to tax expenditures on personal and corporate income taxes. In the first group, which included Italy, Spain and the United Kingdom, they amounted to 5% to 8% of GDP. In the second, which included France, Germany and the Netherlands, they amounted to only 1% to 3% of GDP. The report did not, however, specify to what extent the gap between the two groups reflected differences in how the benchmark was defined, which greatly limits the relevance of these comparisons.
In November 2022 the IMF published a note on the assessment of tax expenditures. According to national estimates, and subject to all the caveats above, they amounted on average to about 4% of GDP in the countries, advanced or otherwise, that publish this information. France is close to the average on this indicator, but it ranked second for the number of tax breaks identified in 2016–2018 (behind Greece).
2. The work of the Council on Economic Policies (CEP)
The Council on Economic Policies (CEP), a Switzerland-based think tank, has undertaken a major analysis of tax expenditures worldwide. In partnership with the German Institute of Development and Sustainability (IDOS), it has launched a Tax Expenditures Lab, comprising a global database of tax expenditures (the Global Tax Expenditures Database, GTED) and an index measuring the transparency of official national tax expenditure reports (the Global Tax Expenditures Transparency Index, GTETI).
The GTED covers 218 jurisdictions and more than 35,000 tax expenditures, drawn from official government publications. While this information can support analysis and debate, it also shows how difficult international comparisons are. First, benchmark tax systems vary widely between countries. Second, the quality (for example, whether provisions are costed) and the scope (limited to central government or extended to the rest of general government; limited to certain taxes or covering all compulsory levies) of official reports are very heterogeneous. In addition, governance arrangements (procedures for creating or abolishing provisions, frequency of evaluations, etc.) often have country-specific features.
The GTETI aggregates the scores given to each country on five criteria, each broken down into sub-criteria:
- data accessibility (format, frequency, etc.);
- governance (legal basis for the reports, external scrutiny, etc.);
- the scope of official publications (specific taxes or all taxes, for example);
- the content of these publications (budgetary cost, number of beneficiaries, etc.);
- the evaluation of tax expenditures (frequency of evaluations, etc.).
Of the 116 countries for which the index is calculated, France ranks ninth. The top-ranked countries are Indonesia, South Korea, Australia, the Netherlands and Canada. Although the quality of the information published in France has its shortcomings, it is worse in most other countries. Everywhere, tax expenditures remain a blind spot in public policy, where many measures benefiting particular groups of households or businesses can be found.
To further improve information on tax expenditures and reduce the comparability problems described above, the CEP has begun publishing country reports written by national experts following a standard outline. The first, published in July 2024, covers the Netherlands and was written by a former deputy director of tax legislation at the Dutch Ministry of Finance. A second report, published in October 2024, covers India. The third, published in November 2024, covers France, and I am its author. It is available online in French and in English. Reports on other countries have since been published.
This note was cited by: Le Point
Note 1. A tax reduction cannot exceed the amount of tax due before the reduction. A tax credit can exceed it, in which case the State refunds the difference between the tax credit and the tax due to the taxpayer.